Mississippi Title Bond Costs
It's incredibly frustrating when you've finally found that perfect ATV or side-by-side, or perhaps you've had one for years, only to realize you don't have the proper paperwork to prove ownership in Mississippi. Maybe the original bill of sale vanished, the manufacturer's certificate of origin (MCO) is long gone, or the machine was passed down without any formal transfer documents. This guide is here to walk you through understanding the costs and process involved in obtaining a Mississippi title bond, a crucial step for many riders to get their machines properly titled when original documents are missing.
Understanding the Need for a Mississippi Title Bond
Navigating the world of ATV and UTV ownership in Mississippi, especially when official documentation is scarce, can feel like you’re trying to ride through a mud bog without 4-wheel drive. A title bond, sometimes called a surety bond, becomes your lifeline in these situations. It's essentially a guarantee to the state of Mississippi that you are, in fact, the rightful owner of your off-road machine, even without the traditional paper trail. If, by some slim chance, another party were to come forward later and prove they are the rightful owner, the bond provides financial protection for them, and the bonding company would then seek reimbursement from you.
Think of it this way: the state wants to ensure clear ownership for every titled vehicle. When a standard document like an MCO for a new machine or a [Mississippi Bills of Sale for a Used Machine] isn't available, a title bond steps in as a form of insurance, safeguarding against potential disputes. This is especially relevant now that [Mississippi ATV Titling Starts July 2025] for newer machines, making clear ownership more important than ever for a wider range of vehicles.
Common Scenarios Leading to a Title Bond
There are several common pathways that lead a Mississippi rider down the road of needing a title bond. It's rarely a path chosen by preference but rather a necessity born from circumstances. Understanding these situations can help you determine if a bond is your next step.
First, and most often, is the case of a lost or damaged Manufacturer's Certificate of Origin (MCO). This is the "birth certificate" for a new machine. If you bought a brand-new ATV or UTV and somehow misplaced this vital document before titling, the state can't verify its initial ownership. Without it, you’re stuck. Similarly, if you purchased a used machine from a dealer who never provided you with the MCO (and it was never titled), you'd also run into this issue.
Another frequent culprit is a lost Bill of Sale from a private seller. Many transactions, especially for older quads or side-by-sides, happen between individuals, perhaps with a handwritten bill of sale or even just a handshake. Years later, when you decide to voluntarily title your older machine (or if it falls under the new mandatory titling rules), that crucial paper has vanished. Without it, you can't prove legitimate transfer of ownership. This is a common challenge for those looking into [Mississippi Voluntary Titles for Older Machines].
Then there's the more ambiguous situation of purchasing a machine with no history or prior title documents at all. This might happen with machines bought at auction, inherited, or simply acquired from someone who never bothered with paperwork. If the vehicle was never titled, and there's no MCO or valid bill of sale to trace its lineage, a title bond is often the only way forward. This also applies to [Titling a Quad You Bought at an Auction] where clear provenance might be lacking.
Finally, you might find yourself needing a bond for inherited machines with missing paperwork. When a loved one passes away and their off-road machine is part of the estate, the legal transfer of ownership requires specific documentation. If those documents are nowhere to be found, a title bond can bridge that gap, allowing the heir to title the machine in their name. Essentially, any time the state can't get a clear picture of who legitimately owns the machine through standard documentation, a title bond acts as your sworn statement backed by financial security.
How Mississippi Sets Title Bond Requirements and Value
When you need a title bond in Mississippi, you can't just pick a random number. The state, specifically through the Department of Revenue working with your local [Mississippi County Tax Collectors and Titles], has a pretty clear method for determining how much that bond needs to be. This isn't just an arbitrary figure; it's designed to provide ample protection for all parties involved.
The most critical factor influencing your title bond amount is the current fair market value of your ATV or UTV. The state isn't going to base it on what you think it's worth, or what you paid for it years ago. They want a realistic, up-to-date assessment. On top of that, Mississippi typically requires the bond to be for 1.5 times the value of the machine. This "multiplier" isn't unique to Mississippi; it's a standard practice in many states and is in place to ensure there's enough financial backing to cover not just the machine's value, but also any potential legal or administrative costs should a claim arise against the bond.
It's a process that can feel a bit like detective work, but it's essential for the state to grant you that clean title. Your tax collector will guide you, but it helps to have a good understanding of what they're looking for.
Estimating Your Machine's Value for the Bond
So, how do you figure out what your ATV or UTV is worth in the eyes of the state? It's not always as simple as a quick Google search, especially for older or heavily modified machines. The goal is to establish a credible, objective value.
One of the most common and accepted methods is to consult blue book values. Resources like NADAguides or Kelley Blue Book often have sections dedicated to powersports vehicles, including ATVs and UTVs. These guides provide estimated values based on make, model, year, and general condition, much like they do for cars. Be honest about your machine's condition—is it "excellent," "good," or does it have "fair" wear and tear? This will directly impact the estimated value.
If you have a particularly unique, vintage, or highly customized machine, or if you simply want a more precise figure, you might consider getting a dealer appraisal. Many ATV/UTV dealerships can provide a valuation for a fee. They have the expertise to assess current market trends, the condition of your specific machine, and any aftermarket additions or modifications that might affect its value. This can provide a strong, authoritative number for the bonding company and the state.
Finally, researching comparable sales in the market can also help. Look at online marketplaces, local classifieds, or even recent auction results for machines identical or very similar to yours in terms of make, model, year, and condition. While not as formal as a blue book value or appraisal, this research can help you understand the current market demand and price points, giving you a solid basis for your own valuation. The more evidence you can provide to support your valuation, the smoother the process will be.
The "Multiplier" Effect: Why 1.5 Times?
You might be thinking, "Why 1.5 times the value? Isn't just the value enough?" It's a fair question, and the answer lies in the fundamental purpose of a surety bond. The state isn't just trying to recover the cost of the machine itself if a claim arises; they're also trying to mitigate other potential financial repercussions.
This "multiplier" is designed to create a buffer. Imagine if, after you've obtained your title with a bond, the true rightful owner of the machine suddenly appears. They prove their ownership beyond a doubt. In that scenario, the bonding company would likely pay out to the original owner. However, simply paying the machine's value might not cover everything. There could be legal fees incurred by the original owner in proving their claim, or administrative costs associated with resolving the dispute.
The 1.5 times multiplier ensures that there's an additional layer of financial protection. It acknowledges that the total financial impact of a disputed ownership claim can extend beyond the mere dollar value of the ATV or UTV itself. It's a way for the state to protect consumers and maintain integrity in the titling system, making sure that if something goes wrong, there's adequate coverage for all involved parties. This is part of the robust process behind [How a Mississippi Title Bond Replaces Lost Paperwork].
The Actual Cost of a Mississippi Title Bond
This is often where the rubber meets the road for most riders. What does a Mississippi title bond actually cost out of your pocket? It's important to understand that the "cost" of the bond isn't the entire bond amount (that 1.5 times your machine's value). Instead, you pay a premium, which is a small percentage of that total bond amount. It's similar to how you pay an insurance premium for a much larger coverage amount.
The premium you'll pay is typically a very small fraction, often ranging from 1% to 3% of the bond amount. However, even for lower-value machines, most surety companies have a minimum premium. This means that if your machine is only worth a few hundred dollars, resulting in a low bond amount, you might still end up paying a flat minimum fee, perhaps $100-$200, simply because there's an administrative cost for the bonding company to process the bond regardless of the value.
Several factors will influence your specific premium. Your credit score often plays a role, as bonding companies assess your financial reliability. The higher the bond amount (i.e., the more valuable your machine), the higher your premium will generally be. Also, different bond companies might have slightly different rates, so it can pay to shop around.
Breaking Down the Bond Premium
Understanding how bonding companies calculate your premium can demystify the process. They're taking on a certain amount of risk by issuing the bond, and your premium is designed to cover that risk, along with their operational costs.
First, they will definitively establish the bond amount based on the 1.5x rule we discussed earlier. Then, they apply their internal rates. These rates are influenced by a variety of factors, including the type of bond (vehicle title bonds are considered relatively low risk compared to some other types), the state's specific regulations, and the current market conditions.
The role of credit history is significant. A bonding company sees your credit score as an indicator of your financial stability and your likelihood to fulfill your obligations. A strong credit score will often qualify you for a lower premium rate, as the company perceives less risk. Conversely, a lower credit score might lead to a higher premium or, in some cases, even require collateral.
Even with a low-value ATV or UTV, you should expect to pay a minimum fee. This minimum fee covers the administrative effort involved in underwriting, processing, and issuing the bond. It ensures the bonding company can cover its costs, even if the calculated percentage of a very small bond amount would be negligible. So, don't be surprised if the premium for a $1,000 machine ends up being closer to $100-$150 rather than just $10 or $20.
The Total Out-of-Pocket Expense
While the bond premium is the primary cost, it's crucial to factor in all potential expenses to get a full picture of your total out-of-pocket spending for a title bond. It's never just one line item.
Beyond the premium, you might encounter application fees charged by the bonding company. These are generally small, perhaps $25-$50, but they add to the total. You'll almost certainly need to get certain documents notarized, so budget for notary fees. These are usually just a few dollars per signature, but they can add up if you have multiple forms. In some cases, if the state or the bonding company requires a formal appraisal of your machine's value, you might face appraisal fees, which can be more substantial, depending on who performs the appraisal.
For example, let's say your ATV has an estimated value of $3,000.
- The required bond amount would be 1.5 times that, or $4,500.
- If your premium rate is 2%, that's $90.
- However, if the bonding company has a minimum premium of $150, that's what you'll pay.
- Add in perhaps $25 for an application fee and $10 for notary services, and your total might be closer to $185.
| Machine Value (Estimated) | Bond Amount (1.5x Value) | Estimated Premium (2% of Bond Amt, or minimum) | Additional Fees (Est.) | Total Out-of-Pocket (Est.) |
|---|---|---|---|---|
| $1,000 | $1,500 | $150 (minimum) | $35 (app+notary) | $185 |
| $3,000 | $4,500 | $150 (minimum if 2% is $90) | $35 (app+notary) | $185 |
| $5,000 | $7,500 | $150 (minimum if 2% is $150) | $35 (app+notary) | $185 |
| $10,000 | $15,000 | $300 (2% of $15,000) | $35 (app+notary) | $335 |
Note: These are estimates. Actual costs will vary based on the bonding company, your credit score, and specific fees.
When comparing different bond providers, it's wise to get quotes from a few different surety companies. While many offer similar services, their minimum premiums and specific rates can differ. Keep in mind that some online platforms, like LawDepot, are excellent resources for general legal forms and templates (such as a bill of sale or affidavit of ownership), which you might need to gather as supporting documentation, but they typically don't directly issue surety bonds themselves. You'll need to work with an actual licensed surety bond provider or an insurance agent who offers surety services. Always check with your [Mississippi Title Questions Collectors Hear] for any specific local requirements they might have.
Steps to Obtaining a Title Bond in Mississippi
Getting a title bond might sound like a complex legal dance, but it's a well-trodden path once you understand the steps. The core process involves applying, getting your machine valued, receiving the bond, and then submitting it to the appropriate state office. This will pave the way for you to eventually receive your title, like the standard [Mississippi Title Fee of $9] document.
The first step is usually to determine if a bond is indeed the right solution for your situation. If you genuinely have no other way to prove ownership, then a bond is likely your answer. You'll then work with a surety bond provider to secure the bond itself before taking it to your county tax collector's office.
The Application Process
Applying for a title bond is similar to applying for other types of financial services; you'll need to provide detailed information about yourself and the machine. This is where attention to detail is crucial.
You'll need to fill out a bond application, which typically asks for your full legal name, address, contact information, and sometimes your Social Security Number (for a credit check). The application will also require extensive details about the off-road machine itself: the VIN (Vehicle Identification Number), make, model, year of manufacture, and an estimated value. This estimated value is critical, as it directly impacts the bond amount. Ensure all information is accurate and consistent with any partial documentation you might still have.
As for supporting documentation needed, this can vary slightly by bonding company, but common requests include:
- Any remnants of a bill of sale, even if incomplete or unsigned.
- An affidavit explaining why you don't have the original title or MCO.
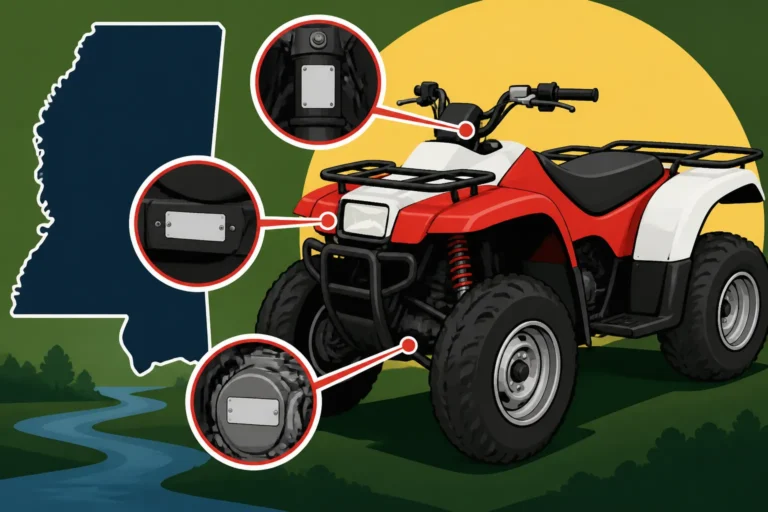
- Photographs of the machine, especially showing the VIN plate.
- Any records of purchase, even informal ones like bank statements.
- A police report if the original documents were stolen.
- Proof of residency in Mississippi.
The more evidence you can provide to support your claim of ownership and explain the missing documents, the smoother the application review process will be. Remember, the bonding company is assessing their risk, and comprehensive documentation helps them feel more confident in you.
Working with a Surety Provider
Finding a reputable surety provider is key to a smooth process. You wouldn't trust just anyone with your financial guarantees, so do a little homework.
You can often find a reputable bond company through various avenues. Many insurance agencies (especially those that handle commercial insurance) also offer surety bonds. A quick online search for "Mississippi title bond" or "surety bonds Mississippi" will yield several results. Look for companies that are licensed to operate in Mississippi and have good reviews. Your local [Mississippi County Tax Collectors and Titles] office might also be able to provide a list of local surety providers they commonly work with or recommend.
Once you've chosen a provider, what to expect from the bond company generally involves a thorough underwriting process. They will review your application, credit history, and the supporting documents you've provided. If everything checks out, they will issue a quote for the premium. Once you accept the quote and pay the premium, they will issue the official title bond document. This document is what you’ll take to the state. It typically includes the bond amount, effective date, and details about the ATV or UTV it covers.
As mentioned earlier, resources like LawDepot can be invaluable when preparing your documentation. While they don't issue the surety bond itself, you might find templates for affidavits, a new [Mississippi Bills of Sale for a Used Machine] if you're trying to document a past transfer, or other legal forms that could be required by the bond company or the state as part of your overall application packet. Always ensure any forms you use from such platforms are filled out accurately and, if necessary, notarized according to Mississippi's requirements.
Submitting Your Bond to the State
Once you have the official title bond in hand, the next step is to present it to the state of Mississippi to initiate the titling process. This isn't something you mail directly to a state capital office; it goes through your local county.
You will submit your bond to your local County Tax Collector's office. This is the same office where you would typically handle vehicle registrations and titling. Along with the original title bond, you'll need to bring your completed title application form (provided by the tax collector's office), any remaining documentation you have (like a bill of sale, even if partial), and proof of identification and residency. This is the stage where you'll also pay the [What a Mississippi ATV Title Costs] and any other applicable fees.
What happens after submission? The process isn't instantaneous. The tax collector's office will review all your submitted documents, including the bond. They will then forward your application to the Mississippi Department of Revenue. There's typically a waiting period, often around six weeks, for a standard title application to be processed. If you're in a hurry, some states offer an expedited or "[Mississippi Fast Track Titles Explained]" service for an additional fee, but confirm if this applies to bond-backed titles. During this waiting period, the state will typically hold the bond, and if no claims are made against it within a specified period (usually three years), the bond's obligation will expire.
Alternative Paths and Considerations
While a title bond is a powerful tool for establishing ownership when documents are missing, it's not always the only path, and there are important considerations once you've secured one. Understanding the duration of the bond and potential alternatives can help you make the most informed decision.
Sometimes, riders jump straight to a bond without fully exploring other options. Before committing to the expense and process of a title bond, it's always worth a thorough search for any original paperwork. A deep dive through old files, calling previous owners (if known), or even contacting the dealership where the machine was originally sold might yield that elusive MCO or bill of sale. If you can locate the original paperwork, you might save yourself the cost and effort of a bond. This is particularly relevant for machines that might fall under the new [ATVs Made After July 2025 Must Be Titled] rule, where clear documentation will be more strictly enforced.
The Bond's Lifespan and Your Protection
A title bond isn't forever, nor is it merely a piece of paper that gives you a title and then vanishes. It has a specific lifespan and a crucial role during that time.
In many states, including Mississippi, a title bond typically has an active period of three years. During these three years, the bond is in full effect, acting as the financial guarantee we discussed. The reason for this specific timeframe is to provide a reasonable window for any potential unknown prior owners to come forward and make a claim against the machine. Three years is generally considered sufficient time for such claims to surface.
What happens if a claim is made against the bond? If, within that three-year period, someone else steps forward with legitimate proof of prior ownership, they can file a claim against your title bond. The surety company would investigate this claim. If the claim is validated, the surety company would typically compensate the rightful owner up to the bond amount. It's crucial to understand that the bonding company will then seek reimbursement from you, the principal on the bond. The bond guarantees the state and potential claimants, but ultimately, it's your financial responsibility if a legitimate claim is made due to your inability to prove initial ownership. This is why it’s so important that you truly believe you are the rightful owner when you seek a bond.
Is a Title Bond Always the Best Option?
While a title bond can be a lifesaver, it's worth considering if it's always the most efficient or cost-effective solution for your specific situation.
Sometimes, the cost-benefit analysis might lean towards other avenues. For instance, if you're dealing with an older, low-value ATV, the minimum premium for a title bond might be a significant percentage of the machine's actual worth. In such a case, you might weigh whether it's truly worth the expense, especially if you only plan to use the machine on private land and don't strictly need a title (though having a title is always recommended for future sales or proof of ownership). However, for machines that fall under the new titling requirements or if you plan to sell it eventually, a title is almost always worth pursuing.
Another consideration is if you have any contact with the previous owner or dealer. If you can track them down, they might be able to help you get duplicate paperwork, like a replacement bill of sale or even a duplicate MCO in some rare cases. This could potentially avoid the need for a bond altogether. Some states also have specific procedures for obtaining a title without a bill of sale through affidavits, but a bond is often preferred by the state for machines with completely absent histories. Always consult with your local tax collector's office about [Mississippi Title Without a Bill of Sale] options before deciding on a bond.
Ultimately, a title bond is a fantastic solution for situations where original documents are genuinely lost or unobtainable, and you need to legally establish ownership in Mississippi. However, taking a moment to confirm you've exhausted all other avenues and understanding the full financial implications and responsibilities is a smart move for any savvy off-road enthusiast.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.